
Quick answer
A gold IRA can work for farmers, but the allocation logic is different from a salaried worker’s
Farm and ranch operators already hold a large share of net worth in land, a physical, inflation-sensitive asset. Adding gold through a SEP-IRA or Solo 401(k) makes sense when you have consistent off-farm liquidity, no plans to tap retirement funds before age 59½, and want to diversify away from both paper assets and the single-commodity risk that farmland carries. Operators carrying heavy operating-loan debt or expecting capital outlays for land or equipment before retirement should keep that cash accessible rather than locking it into a self-directed IRA.
The Real-Asset Problem: Why Farmers Need Different Diversification Math
The case for gold in a retirement account is built on diversification away from paper assets. For most American workers, that logic is clear: a 401(k) invested entirely in equities and bonds has zero physical-asset exposure, and gold can fill that gap. Farmers are different.
A 500-acre corn operation in Iowa carries most of its owner’s net worth in land, grain inventory, and equipment. These are tangible, inflation-sensitive holdings. Land values have historically tracked broad inflation over long periods, meaning a farm family already has significant real-asset coverage. Adding gold to that picture is a smaller incremental step, not the dramatic hedge shift it would be for someone with a teacher’s pension and a brokerage account.
That distinction matters when sizing your allocation. A salaried worker might reasonably allocate 10 to 15 percent of retirement savings to precious metals for diversification. A farm operator with $2 million in land and $80,000 in a retirement account is already tilted heavily toward physical assets. The goal of a gold IRA in this context is narrower: protection against financial-system-specific risks (currency devaluation, banking instability) that even land does not fully hedge, and diversification of the retirement-account layer away from equities.
One additional risk that gold specifically addresses for agricultural producers: commodity price correlation. Farmland values in many regions track agricultural commodity prices. In a sustained commodity bear market, both land values and farm income can compress at the same time. Gold has historically had a low correlation to agricultural commodity cycles, making it a genuine diversifier within the real-asset category itself.
Who Should Not Open a Gold IRA: The Disqualifiers
Before reviewing the funding mechanics, it is worth being direct about when a gold IRA is the wrong tool for a farm or ranch operation.
Operators carrying operating-loan debt should prioritize paying down interest-bearing lines of credit before locking cash into an IRA. IRA funds are illiquid before age 59½ without paying a 10 percent early withdrawal penalty under Internal Revenue Code Section 72(t), plus ordinary income tax. Paying down a 7 or 8 percent operating loan is a guaranteed, tax-free return that most investment vehicles cannot match.
Operators expecting capital outlays before age 59½ face the same constraint. If you plan to buy an adjacent parcel, upgrade irrigation, or refinance equipment in the next five to ten years, that cash needs to stay accessible. Tying it up in a self-directed IRA to purchase gold bullion traded against a 10 percent penalty and taxes is not rational capital allocation.
Operators without off-farm emergency reserves should build a liquid cushion first. Agriculture is cyclical. A single bad crop year, a cattle disease outbreak, or a commodity price collapse can create immediate cash needs. Standard financial planning guidance suggests three to six months of operating expenses in accessible accounts before committing to retirement vehicles.
Operators in the early farm-building years, typically under 40 with high debt-to-asset ratios, generally benefit more from paying down debt and building equity than from retirement contributions of any kind.
If none of those disqualifiers apply, read on.
Three Ways to Fund a Gold IRA From Farm or Ranch Income
Self-employed agricultural producers have access to retirement plan vehicles with contribution limits far above what a standard IRA allows. There are three primary paths to get cash into a self-directed IRA that can hold physical precious metals.
SEP-IRA: The Lower-Friction Starting Point
A Simplified Employee Pension IRA (SEP-IRA) is the most administratively simple retirement vehicle for self-employed farmers and ranchers. You open one at a financial institution, contribute during tax season, and deduct the contribution on Schedule 1 of your Form 1040.
For self-employed individuals, the contribution limit is up to 25 percent of net self-employment income, defined as net profit from Schedule F after subtracting half of your self-employment tax (IRS Publication 560 covers the calculation in detail). The dollar cap for 2025 is $70,000, indexed annually. For 2026 limits, verify the current figure at IRS.gov Retirement Topics.
A SEP-IRA can be self-directed, meaning you roll SEP contributions into a self-directed IRA custodian and then direct those funds into IRS-approved physical precious metals. The custodian holds the metals in an approved depository on your behalf. For a deeper look at how this works, see our guide to SEP-IRA gold investing.
The downside: there is no Roth SEP option, and SEP contributions in the same year as employment at another company can create coordination issues. If you have off-farm W-2 income, consult a tax professional about how the two plans interact.
Solo 401(k): Higher Limits, More Flexibility
A Solo 401(k), also called an Individual 401(k) or owner-only 401(k), is available to self-employed business owners with no full-time employees other than a spouse. Farm operators who hire seasonal workers but no permanent full-time employees often qualify.
The contribution mechanics allow two layers. As the employee, you can contribute up to $23,500 in 2025 (the standard 401(k) deferral limit, indexed annually). As the employer, you can add a profit-sharing contribution of up to 25 percent of Schedule F net earnings, subject to the same overall cap as a SEP-IRA ($70,000 for 2025). Participants age 50 and older can add a catch-up contribution of $7,500 in 2025, bringing the combined maximum to $77,500. IRS Publication 560 provides the authoritative limits; verify the current year at IRS.gov.
Solo 401(k) plans can be structured as traditional (pre-tax) or Roth (after-tax). A Roth Solo 401(k) is particularly interesting for farm operators in years with unusually low taxable income, such as a drought year with income averaging applied. For more detail, see our guide to converting a Solo 401(k) to a gold IRA.
The tradeoff: Solo 401(k) plans require more administrative setup than SEP-IRAs and must have plan documents in place before the end of the tax year for which you want to contribute. They also require a Form 5500-EZ filing once plan assets exceed $250,000.
Rolling Over an Old Employer Plan
Many farm operators worked off-farm earlier in their careers and have dormant 401(k) or 403(b) accounts from former employers. Rolling those into a self-directed IRA is one of the cleanest funding paths because it does not depend on current farm profitability.
A direct trustee-to-trustee transfer from the old plan to a self-directed IRA custodian triggers no taxes and no penalties. Indirect rollovers, where a check is issued to you personally, must be completed within 60 days and are subject to 20 percent withholding that must be made up out of pocket. The direct transfer eliminates both risks. Our gold IRA rollover guide covers the full process step by step.
Farm Income Averaging and Contribution Timing
Agricultural income is lumpy. A wet spring, a drought, a commodity price spike, or a bumper crop year can push Schedule F net income far above the five-year average in a single year. That volatility creates a planning opportunity that most retirement guides ignore.
Internal Revenue Code Section 1301 allows eligible farmers and fishermen to elect income averaging over three prior base years using Schedule J on Form 1040. When income averaging lowers the effective tax rate on a high-income year, it also affects the tax benefit of a deductible retirement contribution in that year. The calculation is not intuitive: in some cases, maximizing a SEP-IRA contribution in a high-income year with income averaging applied produces a lower marginal deduction benefit than contributing in a moderate year without averaging. A tax professional with agricultural clients can model this.
The practical takeaway for gold IRA funding: do not automatically contribute the maximum in a boom year. Model the after-tax cost of the contribution both with and without Schedule J averaging before deciding on the contribution size. And remember that SEP-IRA contributions can be made up to the tax filing deadline plus extensions, which gives farm operators several months after the end of the year to see final income numbers and tax advisor modeling before committing.
Solo 401(k) employee deferrals, unlike SEP contributions, must be elected by December 31 of the plan year. Employer profit-sharing contributions can be made up to the filing deadline. This split timing is another reason some farm operators prefer the Solo 401(k) for maximum flexibility.
What Farmland, Equipment, and Livestock Cannot Do
A common question from farm operators new to self-directed IRAs: can I contribute my land or equipment directly to avoid the cash funding requirement?
The answer is no. Internal Revenue Code Section 408(a) limits IRA contributions to cash, check, or money order. You cannot contribute property in kind, whether farmland, machinery, grain inventory, or livestock. The IRA must receive cash, and the custodian then uses that cash to purchase approved assets, in this case physical precious metals in approved form.
Farmland cannot be held inside a standard IRA either. Self-directed IRAs can hold real estate, but that is a separate vehicle from a gold IRA, and mixing the two in a single account creates prohibited transaction risks under IRC Section 4975. Attempting to lease IRA-owned land back to yourself or your farming operation is a textbook prohibited transaction that would disqualify the IRA and trigger immediate taxation of the entire account value. Do not attempt it without detailed legal advice.
The cleaner approach is to keep farmland and equipment in the operating entity or family trust, and treat the IRA as a separate financial-asset layer that holds metals outside the agricultural operation.
What Goes Inside the Precious Metals IRA
Not all gold and silver products qualify for IRA inclusion. Internal Revenue Code Section 408(m)(3) requires that gold meet a minimum fineness of 0.9950 and silver meet 0.9990, with specific exceptions for certain government-minted coins.
Qualifying gold products include American Gold Eagle coins (which receive a statutory exemption from the fineness requirement despite being .9167 fine), American Gold Buffalo coins (.9999 fine), Canadian Gold Maple Leaf coins (.9999 fine), and gold bars or rounds of .9999 fineness produced by a recognized refiner or assayer. Qualifying silver products include American Silver Eagle coins, Canadian Silver Maple Leaf coins, and silver bars or rounds meeting the 99.9 percent purity standard.
Collectible coins, numismatic items, and coins whose value is based primarily on rarity rather than metal content do not qualify. Your custodian maintains a list of approved products, and purchases go through an IRS-approved dealer with the metals shipped directly to the custodian’s designated depository.
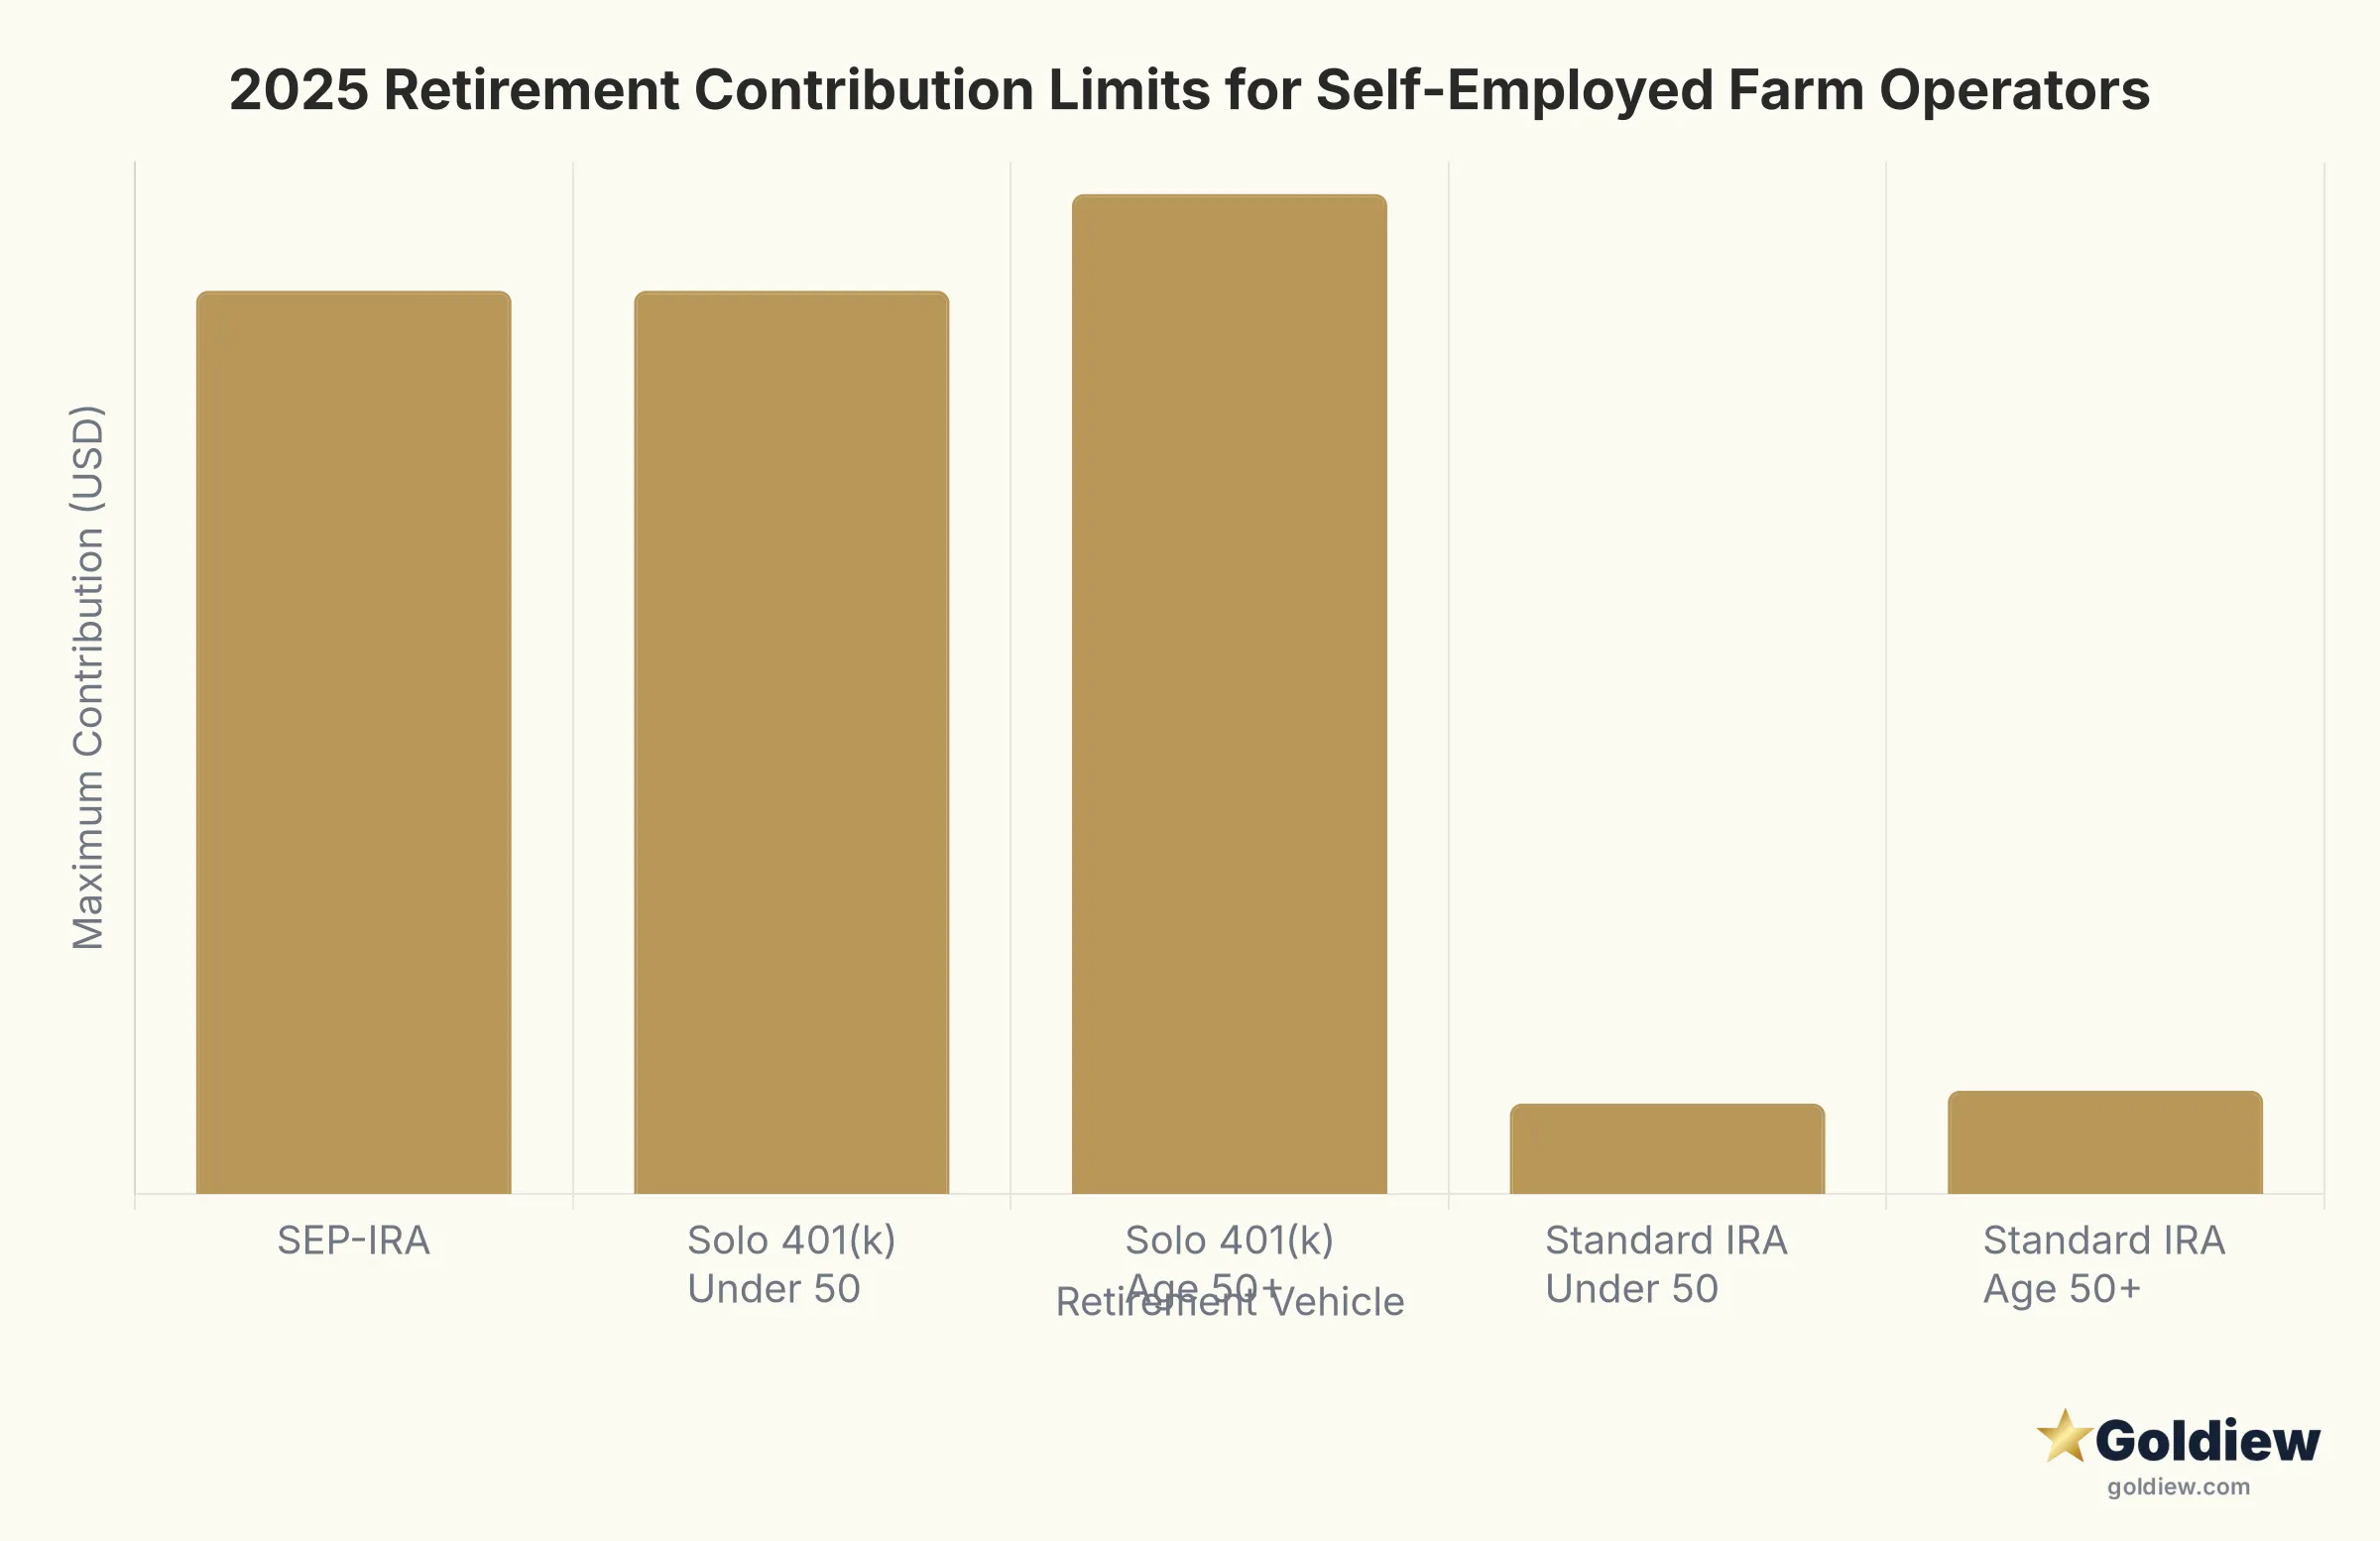

| Vehicle | 2025 Max Contribution | Catch-Up (50+) | Roth Option | Admin Complexity | Contribution Deadline |
|---|---|---|---|---|---|
| SEP-IRA | Lesser of $70,000 or 25% of net SE income | None | No | Low | Tax filing deadline + extensions |
| Solo 401(k) | Up to $70,000 (employee + employer) | +$7,500 | Yes | Moderate | Dec 31 (deferrals); filing deadline (profit-sharing) |
| Rollover from old employer plan | No limit (existing balance) | N/A | Depends on source plan | Low (direct transfer) | No deadline (direct transfer) |
| Traditional / Roth IRA | $7,000 (2025) | +$1,000 | Yes | Very low | Tax filing deadline + extensions |
Source: IRS Publication 560 (2025). Limits indexed annually; verify current year at IRS.gov.
Taking the Next Step
If you clear the disqualifiers listed above and have identified a funding source, the process begins with selecting a custodian who specializes in self-directed IRAs for physical precious metals. The custodian holds the account, purchases the metals on your direction from an approved dealer, and arranges for storage at an IRS-approved depository. You never take personal possession of the metals while they are inside the IRA.
Augusta Precious Metals works specifically with individuals converting existing retirement accounts or setting up new self-directed IRAs for physical gold and silver. Their education-first process includes one-on-one sessions with a salaried, non-commissioned educator before you make any commitment. Augusta has held a BBB A+ rating with zero complaints since accreditation in 2014 and has received Money Magazine’s Best Overall Gold IRA Company designation from 2022 through 2026.
Get Augusta’s Free Gold IRA GuideFrequently Asked Questions: Gold IRA for Farmers and Ranchers
Can I use Schedule F income to fund a SEP-IRA or Solo 401(k)?
Yes. Net profit from Schedule F qualifies as self-employment income for retirement plan contribution purposes. You subtract half of your self-employment tax from net Schedule F profit to arrive at the compensation figure used in the SEP-IRA contribution formula. IRS Publication 560 walks through the exact calculation. If you also have W-2 income from off-farm employment, the contribution limits are coordinated across plans, so model total contributions with a tax professional.
Can my farming LLC or S-corp fund a gold IRA?
It depends on the entity type. A single-member LLC treated as a disregarded entity files on Schedule C or F, and the owner can open a Solo 401(k) or SEP-IRA based on that net income. An S-corporation pays the owner a reasonable salary (W-2), and the retirement plan is sponsored by the corporation, not the individual. In either case, the retirement plan account itself is individual and can be directed into a self-directed IRA holding precious metals. Multi-member LLCs or partnerships create additional complexity around plan eligibility for each partner. Consult a CPA familiar with agricultural entities before selecting a plan structure.
Does income averaging under Schedule J reduce my allowed SEP-IRA deduction?
Income averaging under IRC Section 1301 affects your tax rate in the election year, not the contribution limit itself. The SEP-IRA deduction is still calculated on actual Schedule F net income, not the averaged figure. However, averaging can change the marginal tax benefit of the deduction because it shifts income across tax brackets. In some high-income years with averaging applied, the deduction is worth less at the margin. Model both scenarios before deciding on contribution size for the year.
What happens if I need cash from my gold IRA for a farm emergency?
Withdrawing from an IRA before age 59½ triggers ordinary income tax plus a 10 percent early withdrawal penalty under IRC Section 72(t), unless an exception applies. Exceptions include disability, death, certain substantially equal periodic payment arrangements, and a handful of others, but a farm cash-flow emergency is not among them. Physical gold inside the IRA also cannot be quickly liquidated the way a brokerage account can, adding a practical delay. This is why maintaining a separate off-farm liquid reserve is a hard prerequisite before opening a gold IRA.
Can I store gold IRA metals on my farm property?
No. IRS regulations under IRC Section 408(m) require that precious metals held in an IRA be in the physical possession of an IRS-approved trustee or custodian, which means storage at an IRS-approved depository. Taking personal possession of the metals, including storing them on your farm, property, or in a personal safe, is treated as a distribution and triggers immediate taxation plus penalties. The IRS has litigated this point successfully in Tax Court (see McNulty v. Commissioner, 157 T.C. No. 10 (2021) for the definitive ruling on home storage arrangements). Metals must go to a commercial depository.
Is there a Roth option for farmers who want tax-free growth?
A Solo 401(k) can be structured with a Roth component, allowing after-tax employee deferrals that grow tax-free. SEP-IRAs do not have a Roth option (though the SECURE 2.0 Act created a pathway for employer SEP contributions to be designated Roth, subject to plan adoption; consult your plan administrator). Standard Roth IRA contributions are also available up to the annual limit ($7,000 for 2025, phasing out at higher income levels). Roth treatment is particularly valuable for farmers in low-income years who expect higher income later in retirement, since withdrawals of qualified distributions are completely tax-free under IRC Section 408A.
Do I need a separate EIN to open a Solo 401(k) for my farm?
Yes. A Solo 401(k) plan must be established in the name of a business, and most plan custodians require an Employer Identification Number (EIN) even for sole proprietors. Obtaining an EIN for a sole proprietorship farm is free and takes minutes at IRS.gov. If your farm already files with an EIN (common for farms with employees, even seasonal ones), you use the existing number. The EIN for the plan is separate from any LLC or corporate entity EIN you may already hold.
How does a gold IRA affect my Required Minimum Distributions in retirement?
Traditional SEP-IRA and pre-tax Solo 401(k) accounts are subject to Required Minimum Distributions starting at age 73 under the SECURE 2.0 Act (age 75 for those who reach age 73 after December 31, 2032). A gold IRA holding physical metals requires the custodian to calculate your RMD based on the fair market value of the metals as of December 31 of the prior year. The RMD can be satisfied by selling a portion of the metals inside the account and distributing cash, or by taking an in-kind distribution of a portion of the physical metals (which becomes a taxable event at FMV). Physical metals require more planning around RMDs than a cash-equivalent investment because liquidity is not instant.
Sources
- IRS Publication 560: Retirement Plans for Small Business (SEP, SIMPLE, and Qualified Plans)
- IRS: One-Participant 401(k) Plans
- IRS Retirement Topics: SEP Contribution Limits
- IRS Publication 590-B: Distributions from Individual Retirement Arrangements
- IRS Schedule J: Income Averaging for Farmers and Fishermen
- 26 U.S.C. § 408: Individual Retirement Accounts (IRA contribution rules and eligible assets)
- 26 U.S.C. § 408(m)(3) (Precious metals fineness requirements for IRA eligibility)
- 26 U.S.C. § 72(t) (10 percent early withdrawal penalty and exceptions)
- 26 U.S.C. § 1301 (Income averaging for farmers)
- McNulty v. Commissioner, 157 T.C. No. 10 (2021) (IRS trustee-possession rule for IRA metals; home storage ruled a distribution)
- IRS: Roth IRAs (IRC Section 408A, Roth IRA rules)